All Categories
Featured
Table of Contents
Nationwide also offers you the ability to essentially purchase extra upside prospective with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage investment techniques, which feature an additional 1%-2% fee. Although this reduces an IUL's flooring listed below 0%, there may be years when you desire the extra benefit potential. Diverse Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-lasting development, however uninspired early money valuesParticipating policy loan rate is capped to be no higher than 8% Columbus Life Insurance Coverage is the IUL arm of the well-rated insurance coverage corporation of Western Southern Group, which went into the IUL arms race in the middle of the last years.
Since their only responsibility as a company is to the long-lasting commitment of insurance policy holders, they are most likely to do right by their inforce block of organization. This can be clearly seen in this screenshot we just recently sent out to among our customers revealing how Columbus Life's IUL cap rates have progressively increased from 8.75% in December 2022 to 10% exactly one year later as rates ticked up.

The worst IUL business continuously declare to have the very best Indexed Universal Life insurance policy with the greatest cap. However, they'll start with a really high cap to catch market share, then quickly pull the carpet out from under their consumers once they shelve that item and start a brand-new one.
That way, policyholders obtaining for outdoors financial investment chances still had the prospective to earn at least some favorable arbitrage. Strong S&P 500 cap rateParticipating loan rate is capped at 6% (but has actually been lower for a while)Their recorded history of dealing with in-force insurance policy holders fairlyMutual Holding Business without any outside stockholdersTheir uncapped indexed account is currently unsightly and inactionable.
To clarify, all the very best IUL business in this post offer some sort of totally free persistent illness rider, however National Life Group's is arguably the most robust. I also want to point out that I am specifically discussing their "Peak Life" product, which is their "bigger case" product using a more structured charge structure.
Best Indexed Universal Life Policies for Retirement
Technically the rider is "totally free", but we've discovered when stress-testing costs that the mortality expenses are a bit greater than other of the very best IUL companies. This is to be anticipated, and you may have heard me say, "There's rarely any deals in insurance. Whatever gets priced perfectly rather rapidly."That said, National Life Group remains in the running for the very best Indexed Universal Life insurance coverage company for customers trying to find a balance of performance, earnings, and thorough protection.
Do not spend excessive time on these details as your numbers will definitely differ, but this shows the type of persistent illness rider payments they offer. to discover which are presently the very best IUL policies with robust Chronic Illness Riders and strong IUL crediting techniques for tax-free earnings if you do not become too sick or injured to work independently.
Indexed Universal Life Insurance coverage has so numerous moving parts at its core, not to discuss all the possible bells and whistles different business add to their policies. If you're weighing IUL versus your existing retirement accounts, our complete breakdown of covers the crucial distinctions in contribution limits, tax treatment, and flexibility.
Throughout most of the 1900s the only life insurance products were Whole Life and Term. Term insurance supplied lower costs for momentary life insurance coverage. Whole Life offered an ensured death benefit for a guaranteed level premium, but likewise had actually a connected savings element with a guaranteed irreversible growth rate in addition to non-guaranteed dividends.
Low-Cost Individual Health Quotes
The idea with Universal Life is that the development of the cost savings account will minimize the quantity of pure insurance coverage in the policy, which would reduce the rising cost per system of death advantage. In 1986, shortly after the meteoric rise of Universal Life, life insurance companies had the idea of including a financial investment component.
This caused the internal revenue service restricting just how much premium anyone could pump into any quantity of permanent death advantage for future tax-free retirement earnings. Regardless, as the stock exchange raved on throughout the 1990s, VUL became the insurance coverage item of option for cash build-up. In 1997, the very first Indexed Universal Life item was created by TransAmerica (not on the list of 2026 Best IUL companies). At initially, Indexed Universal Life insurance coverage didn't make a huge splash at all.

Latest Posts
Understanding How Whole Life Insurance Builds Cash Value
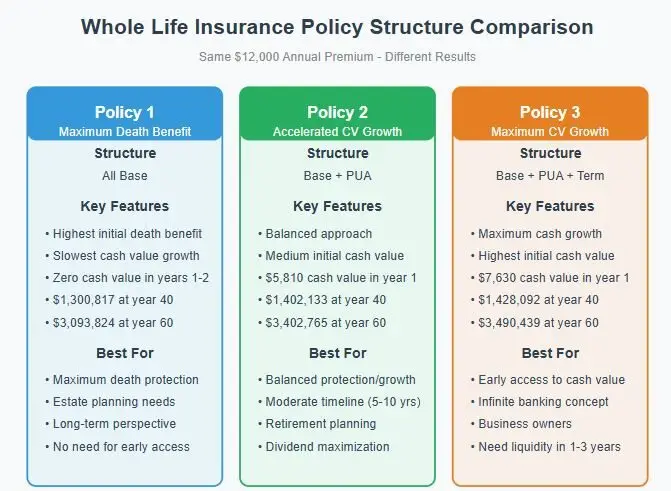
The Mechanics of Whole Life Coverage
Selecting Your Top 2026 Medicare Supplement Coverage